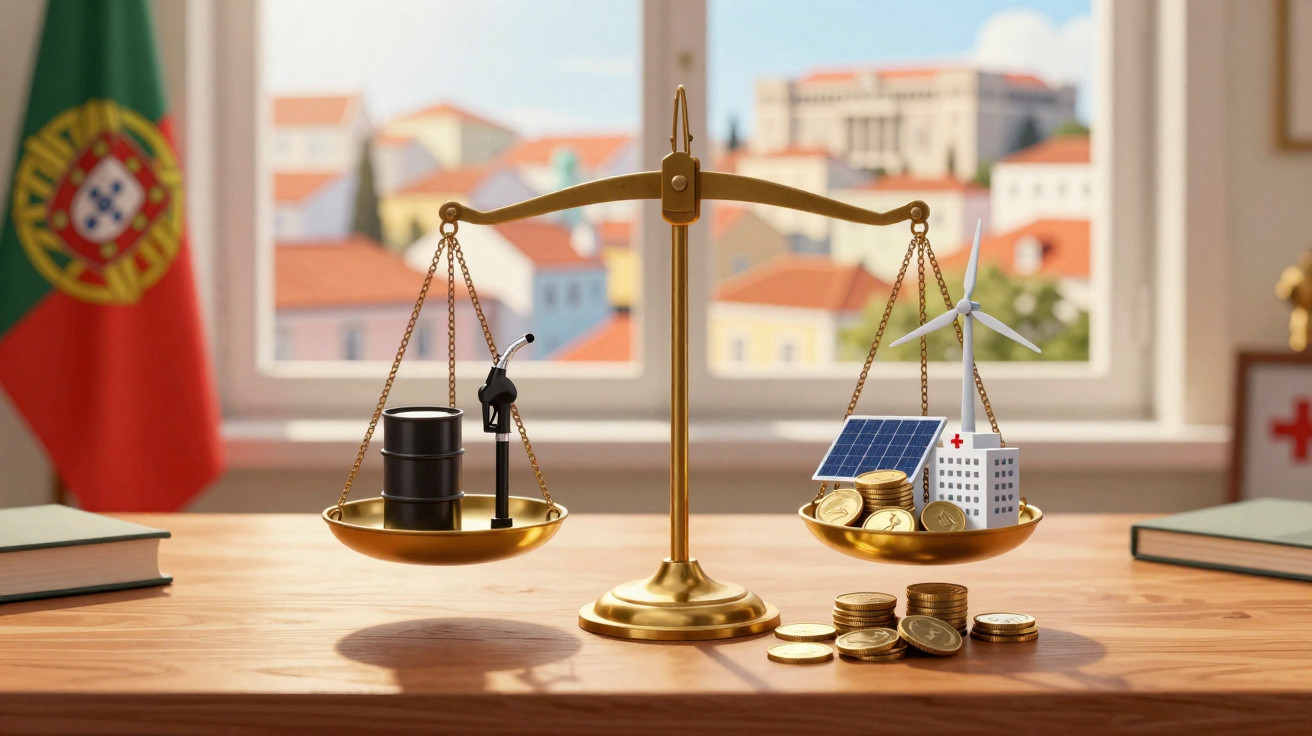
Under fire over its response to soaring fuel prices, the Government is now moving forward with an extraordinary levy on oil companies’ profits.
The proposal has already been submitted to the Assembly of the Republic. It sets out how much companies may have to pay and, above all, the profit threshold from which the charge will apply.
The measure covers businesses involved in crude oil extraction and the refining of petroleum products. Where profits in 2026 exceed a specified level, part of those profits will face an exceptional 33% rate. Crucially, however, not all of a company’s profits will be taxed at 33%.
How does the rate work?
To understand the scheme, it is best to begin with the previous two years. The Government will calculate the average taxable profits recorded in 2024 and 2025, then compare that figure with the company’s 2026 profit. Only the amount exceeding that average by more than 20% will count as extraordinary profit and be subject to the new levy.
For instance, if a company’s average taxable profit for 2024 and 2025 was €100 million, its 2026 threshold would be €120 million. If it makes €150 million this year, the €30 million above the €120 million threshold is the amount included in the calculation for the extraordinary levy.
In other words, the 33% rate would not be charged on the full €150 million profit, but solely on the €30 million classified as extraordinary.
The charge is called the Temporary Solidarity Contribution on the Petroleum Sector (CSTSP) and will apply only to the 2026 tax period. The proposal must still be debated and approved by Parliament.
What if an oil company has made losses?
A separate rule applies in that circumstance. If the average taxable profits for 2024 and 2025 are negative, the Government will treat that average as zero for the purposes of the contribution.
In practice, a company that made losses in each of the preceding two years but reports a profit in 2026 could have all of its 2026 taxable profit subject to the 33% charge.
There is also a specific provision for refineries. The Government wants to ensure that the way companies account for the cost of oil used in production does not materially alter the profit amount considered under this contribution.
To achieve this, the positive difference arising from the use of the FIFO (First In, First Out) method for petroleum products consumed in refining may be added to taxable profit.
Put simply, the State will carry out an additional check on how refineries calculate profit, preventing differences in the accounting treatment of petroleum product costs from reducing the amount subject to the contribution.
Where will the money go?
Under the proposal, the revenue raised will be allocated to the Environmental Fund and the Institute for the Financing of Agriculture and Fisheries.
The funds will support measures linked to fossil fuels, particularly assistance for households, humanitarian fire brigade associations and organisations in the social sector.
Support measures are also planned for freight and passenger transport businesses with public service obligations. The Government justifies the contribution by pointing to the effect of higher fuel prices on households and businesses, as well as the increased profit margins seen in the petroleum sector.
In the proposal, the Executive argues that these additional profits stem mainly from changed market conditions, rather than necessarily from new investment or efficiency gains.
A measure already announced
The creation of this contribution had already been approved by the Council of Ministers at the end of July. Now that the proposal has been lodged with Parliament, the detailed rules for deciding which share of profits will be treated as extraordinary have been set out.
The measure follows the European Commission’s authorisation for Member States to introduce their own levies on the extraordinary profits of energy companies. Portugal has meanwhile advocated a common European-level solution alongside other countries.
For now, however, the contribution remains only a proposal. It must still pass through Parliament before becoming law.
Comments
No comments yet. Be the first to comment!
Leave a Comment